About Us
- Home
- About Us
We are a team of world-class reputed and renowned experts (practitioners, professors, industry and academic pioneers) from across the world in the field. Some of them are mentioned below.
We serve institutions, fund management firms, portfolio managers, risk management firms, banking institutions, academic and research institutions, policymakers, professionals and people from across industries e.g. health, medical, finance etc. including from some of the top institutions of the world among others.
Disclaimer: We don’t provide any type of end to end investment advisory services or manage public funds etc. We just assist in Quantitative ,Statistical & Risk Management consultancy and practical skill development.
Our Team
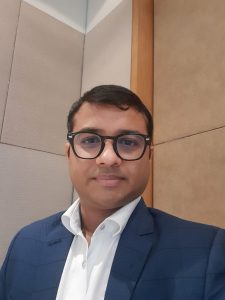
Pankaj Mani is the Founder and MD at RealWorldRisk . He is also the Co-founder of India’s only Quant Association (LAQSA-IndiaQuant) supported by renowned global and local institutions. He is the President of CQF-India(Delhi) Society, the world’s largest and reputed Quant Finance community founded by the renowned legend Dr. Paul Wilmott (Oxford University). He is Executive Committee Member- the globally recognised body Global Association of Risk Professionals (GARP)- India Chapter.
He is also the research author for the world’s prestigious Quant Finance & Risk Magazine Wilmott(Wiley Publishing ) for deep influential seminal works, this is where leading Globally Renowned Quant veterans publish on some new influential works. He is also the author of the randomly written book – Scientific Investing in the Real-World: Black Swan & Tail Risk. He has written many scholarly deep research works. He is also interviewed by some of the leading newspapers and online platforms e.g. The Economic Times.
His areas of expertise are into unconventional Quant, Quantamental,Quant+ Fundamental, Portfolio, Risk, Investment, AI/ML, Randomness, Causality, Convexity, Performance Analysis, Non-Linearity , Scientific Factors based Strategies, Human Behavioural scientific dynamics, Happiness,Stress-adjusted strategies, AI/ML, ESG,Risk Management, Tail Risk, Black Swan etc. His practical portfolio Strategies have done quite well over the years successfully handling Black Swans and many tail events without much stress and worrying about future of markets in mindful ways.
He has deeply interacted and collaborated with many world-renowned experts and locally as well e.g. Nobel Laureate, Renowned Professors, Global Best Selling Authors, Senior Government Advisors & Policymakers, Fund Managers, Academicians etc..
He often speaks and trains at national and internationally reputed platforms having participants from leading and top global and local financial institutions, universities, government institutions e.g. Goldman Sachs,RBI, SBI, ICICI , Columbia University, NYU, IITs, IIMs, ISI, CFAs among others. His thoughts are also covered by some of the leading newspapers like The Economic Times.
He has also keen research interests in Philosophy, Spirituality, Nature, Social dynamics, Neuroscience, Consciousness among others.
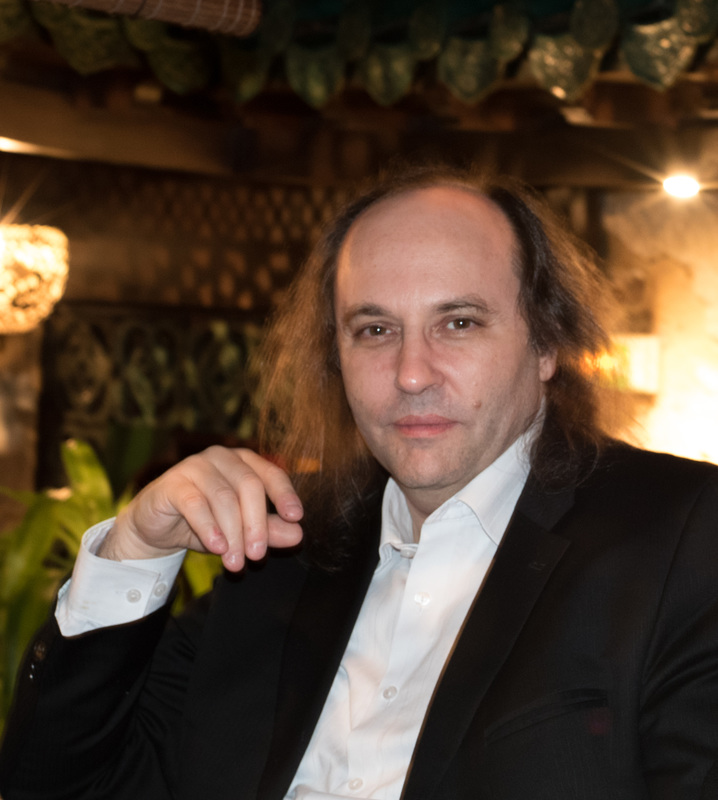
Prof. Raphael Douady is a world- renowned quant, mathematician,statistician and economist specializing in data science, financial mathematics and chaos theory at the University of Paris I-Panthéon-Sorbonne. He formerly held the Frey Chair of quantitative finance at Stony Brook University and was academic director of the French Laboratory of Excellence on Financial Regulation. He earned his PhD in Hamiltonian dynamics and has more than 25 years of experience in the financial industry. He has particular interest in researching portfolio risks, for which he has developed especially suited powerful nonlinear statistical and data science models, as well as macroeconomics and systemic risk. He is the Mathematical Founder with Prof Nassim Taleb on AntiFragility Theory( in context of Black Swan , Extreme risks) and other industry training works. He has produced many original seminal works including New Non-Linear Polymodel approach to Factor Strategies as significant improvement to traditionally popular factor based approaches. He also advises several quantitative hedge funds and family offices on their risks and trading strategies. Douady is a founding member of the Club Praxis, a New Yorkbased think tank advising the French government on its economic policy and sits on the board and, previously on the investment committee, of Friends of IHES, a foundation supporting the Institut des Hautes Etudes Scientifiques (the French brother of Princeton IAS).He was awarded a gold medal at the International Mathematical Olympiads. His father, Adrien Douady, a renowned mathematician (a close colleague and friend of Benoit Mandelbrot) known for works on Mandebrot set and Douady Rabit and others.
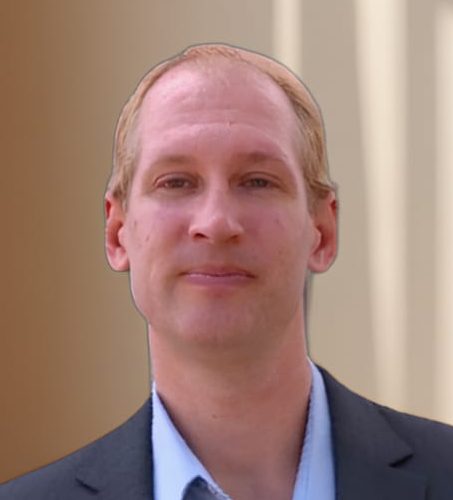
Christopher Grune began his career working for a member firm on the open outcry trading floor at the Chicago Board of Trade (now CME Group). He has over 30 years’ experience in both finance and IT on three continents (Africa, Asia and North America). He holds an MBA from Columbia Business School in New York, is a CFA Charterholder, and also holds the Certificate in Quantitative Finance (CQF), Professional Risk Manager and SIIA Financial Information Associate designations. He served for many years as a founding society member or as a board member of the CFA Societies of both Japan and East Africa. His career spans some of the world’s largest financial institutions, including Citi, Société Générale, State Street and IFC (World Bank Group). As a global emerging market Quant based fund manager, he managed billions of dollars in assets, actively trading on the NSE and BSE. He also ran a global EM market neutral hedge fund where he traded Indian futures and options contracts, as well as shorting and employing stock borrow in all the EM markets. Chris is an author and reviewer for a wide range of finance and IT topics for the Chartered Institute for Securities and Investment (CISI) of the UK and currently conducts assignments dealing with corporate finance advisory, Quant,AI/ML & Risk Management areas and business development across emerging and frontier markets.
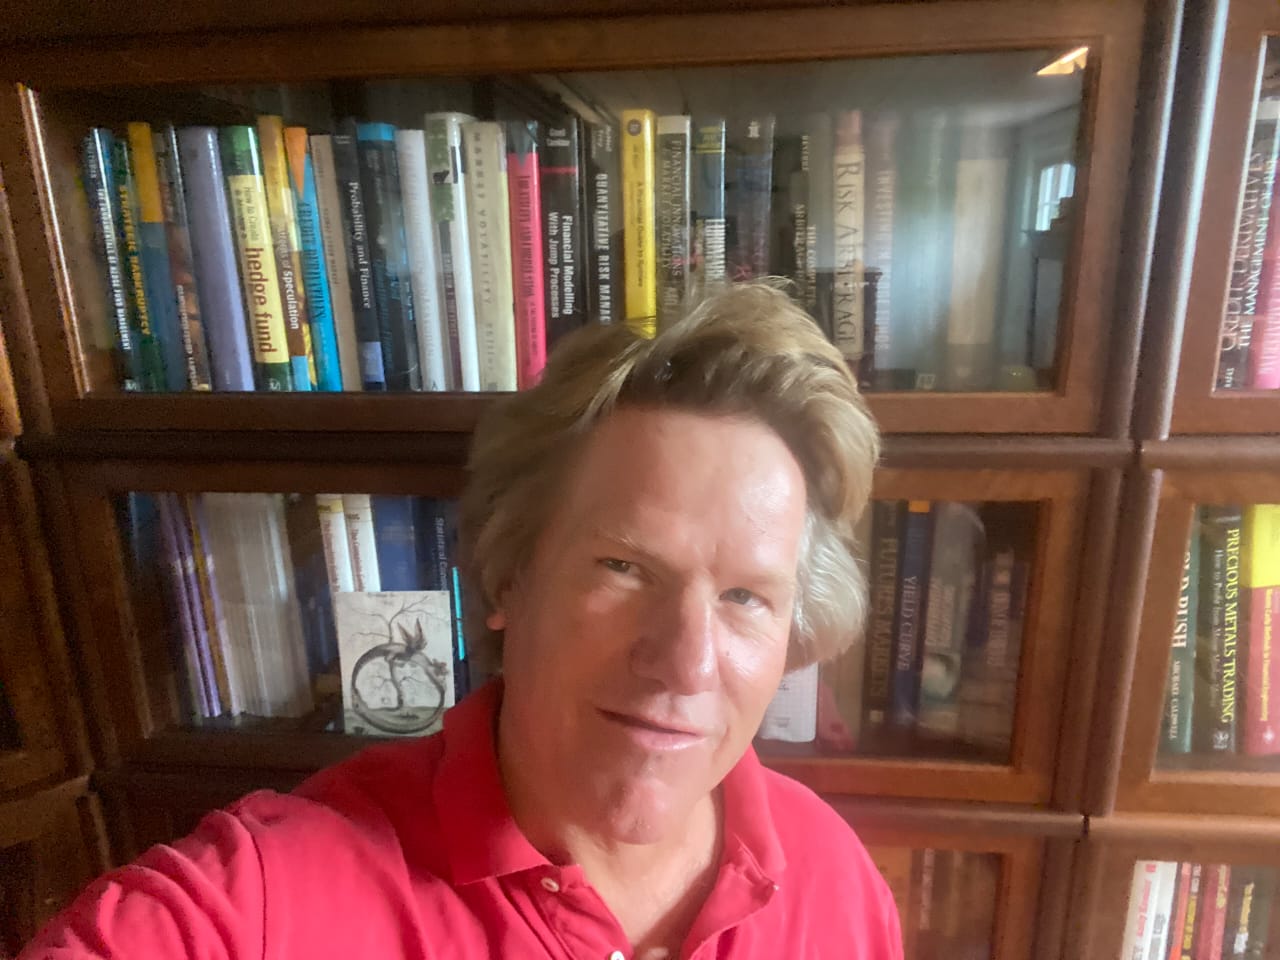
Dr. Espen Gaarder Haug is a world renowned expert who has many years of experience in market making and options trading at banks such as Den norske Bank, Chemical Bank, and J.P. Morgan Chase, as well as at multi-billion-dollar hedge funds like Paloma Partners. He later spent time in academia as a finance professor, while primarily conducting research in theoretical physics. He is now back in finance and is involved in a fintech startup in London focused on options pricing and hedging. Haug is the author of several books, including The Complete Guide to Option Pricing Formulas, Derivatives: Models on Models, and most recently: Wall Street Short Stories: Economic Warfare, Corruption, and Greed.
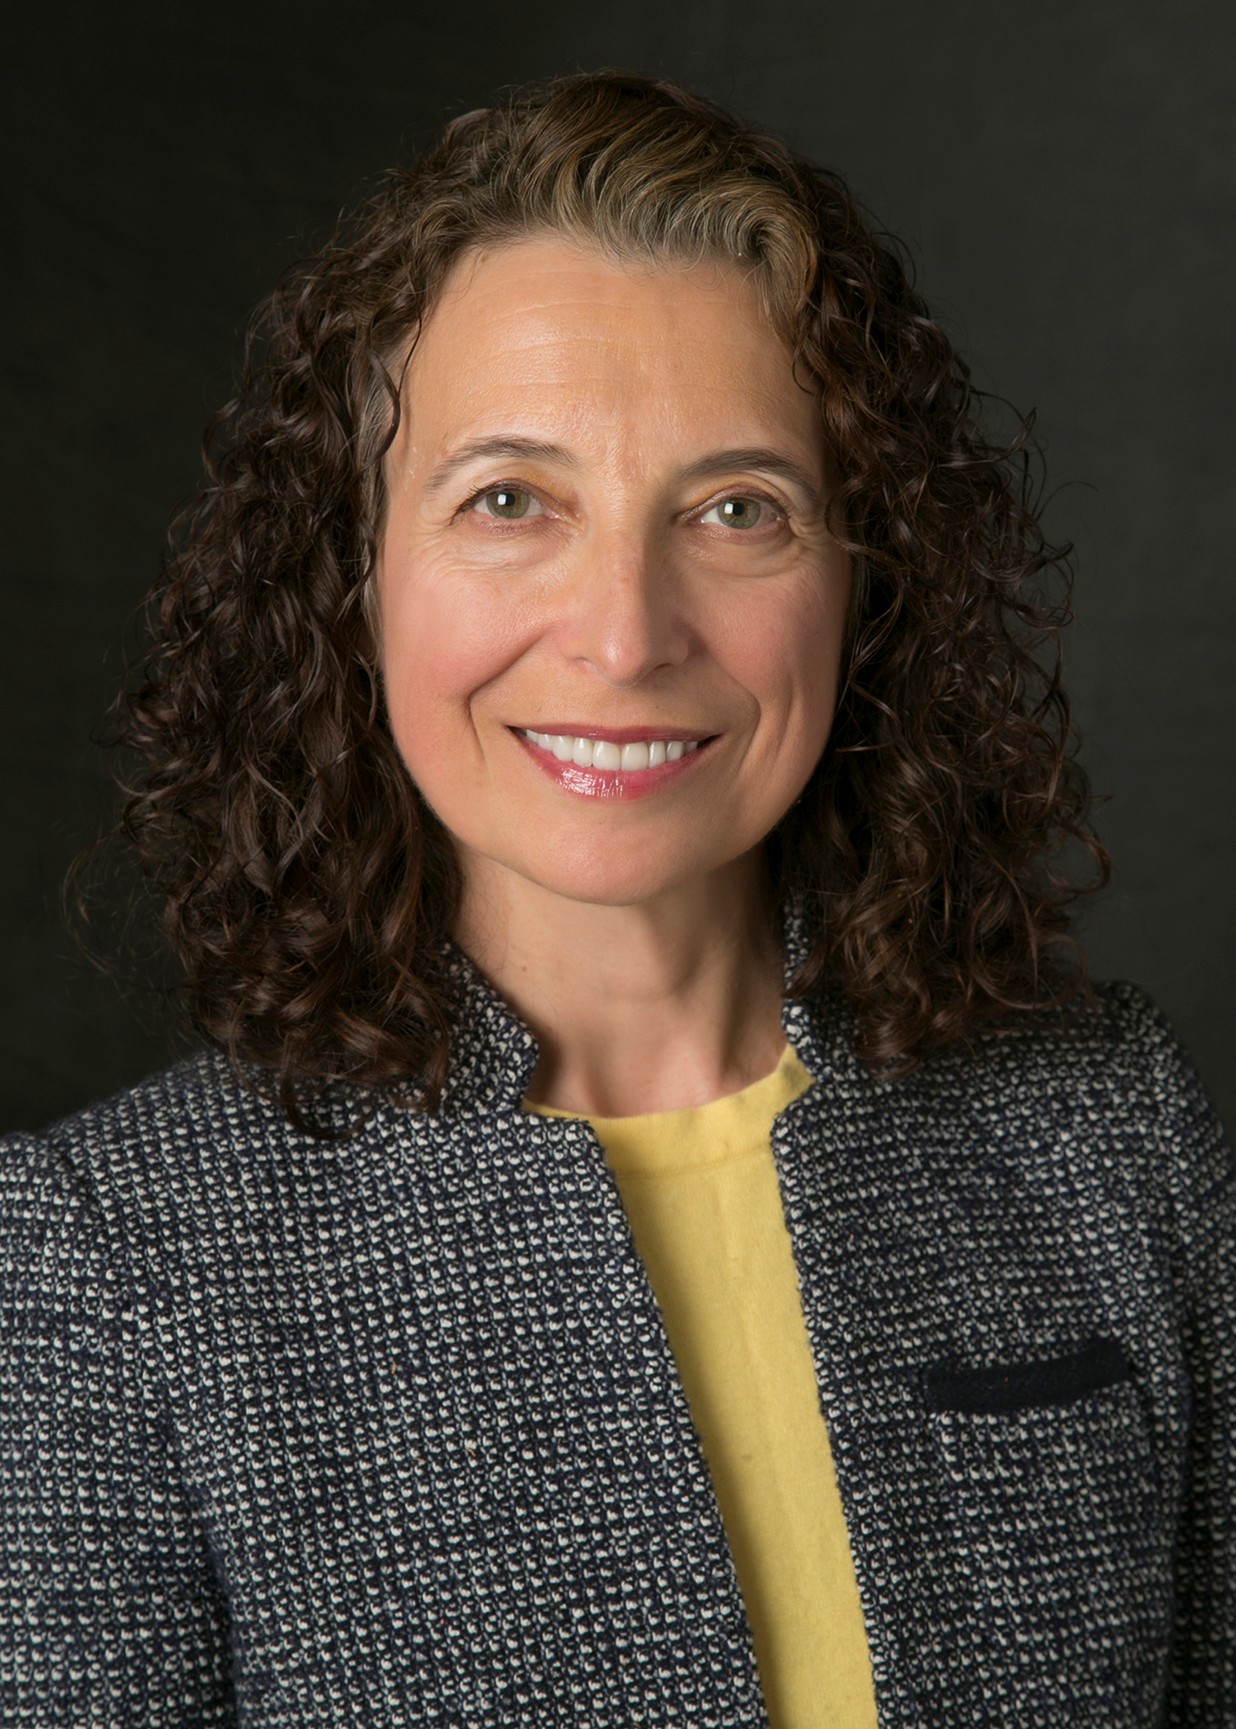
Alla Gil is currently an entrepreneur and CEO. She was previously the Global Head of Strategic Advisory at Goldman Sachs, Citigroup, and Nomura, where she advised financial institutions and corporations on stress testing, economic capital, ALM, long-term risk projections and optimal capital allocation. She has also provided invited trainings at leading organizations like US Govt. Treasury Deptt. etc. She is also columnist for Global Association of Risk Professionals.
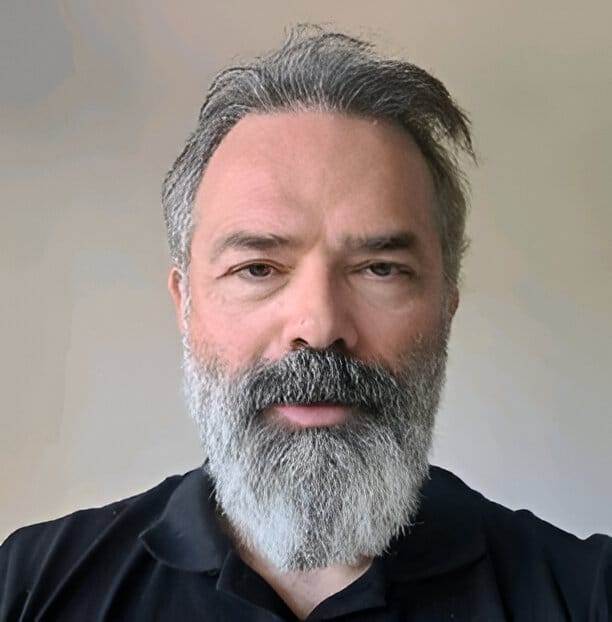
Miquel Noguer i Alonso is a seasoned financial professional and academic with over 30 years of experience
in the industry. He is the Founder of the Artificial Intelligence Finance Institute and Head of Development
at Global AI. His career includes roles such as Executive Director at UBS AG and CIO for Andbank. He has
served on the European Investment Committee UBS for a decade. He is on the advisory board of FDP
Institute and CFA NY.
Mr. Noguer is also an academic, teaching AI, Big Data, and Fintech at institutions like NYU Courant
Institute, NYU Tandon, Columbia University, and ESADE. He pioneered the first Fintech and Big Data
course at the London Business School in 2017. He is the author of 100 papers on Artificial Intelligence.
He holds an MBA and a Degree in business administration from ESADE, a PhD in quantitative finance from
UNED, and other prestigious certifications. His research interests span asset allocation, machine learning,
algorithmic trading, and Fintech. He recently wrote a book Artificial Intelligence in Finance with Risk books
and a Quantitative Portfolio Optimization book for Wiley.
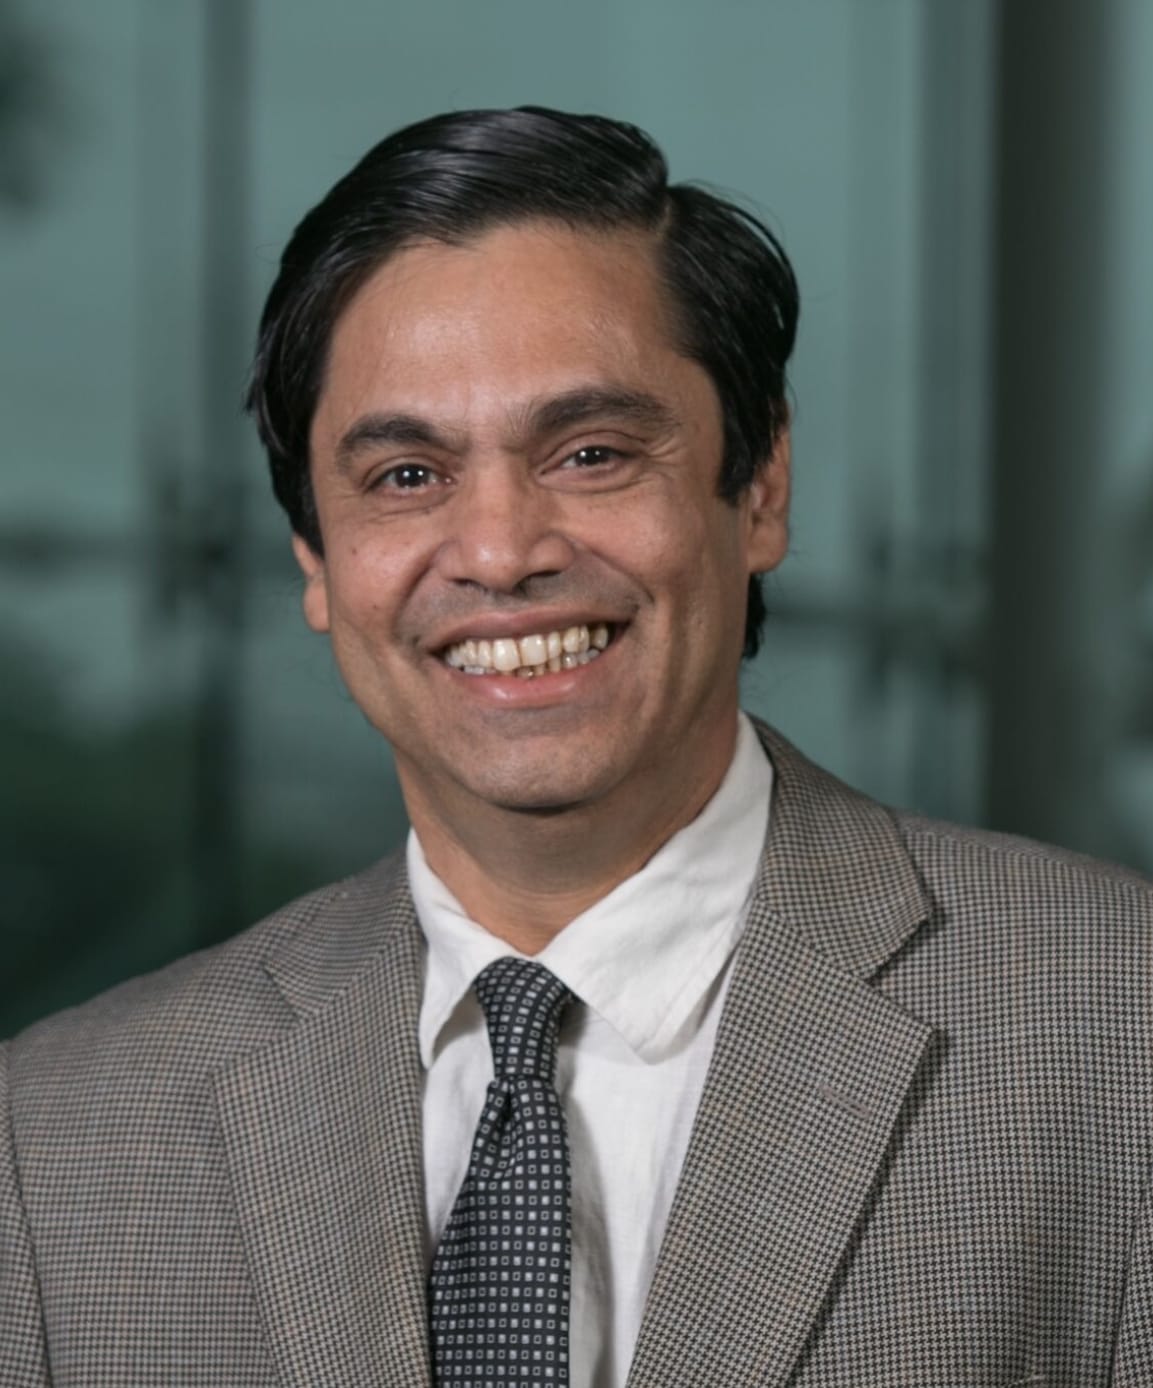
Dr. Suman Banerjee
Stevens Institute of Technology, NY,USA
Formely at Nanyang Business School (NTU),Singapore.
Dr. Suman Banerjee is an Associate Professor of Finance and the director of Ph.D. programs at the School of Business of the Stevens Institute of Technology. He was previously faculty at Asia’s leading NTU ,Singapore (Nanyang Technical University) School of Business and Finance. His research interests include theoretical modeling and empirical analysis with applications to areas of corporate finance such as corporate governance, behavioral corporate finance, risk management, and energy finance. Dr. Banerjee has published extensively in top-tier finance journals like Review of Financial Studies (RFS), Journal of Financial Economics (JFE), Journalof Finance and Quantitative Analysis (JFQA), Journal of Corporate Finance (JCF). Dr. Banerjee also published in top-ranked cross-disciplinary journals like Management Science (MS) and Journal of Business(JB). Dr. Banerjee received the Caeserea Award for the best paper in risk management from the prestigious Western Finance Association in 2002 and BankScope best paper award from the Australian Finance and Banking Conference in 2010. He was honored as a Junior Research Fellow by the Indian University Grants’Commission and Center for Advanced Studies Scholarship while pursuing a master’s degree at Delhi School of Economics. He has obtained several other merit-based awards in the course of his academic career. Dr. Banerjee is a lifetime member of the multiple finance-related national and international associations and the editor-in-chief of an open-access finance journal.He is also a knowledge-based consultant for Bloomberg Inc. and other reputed corporates.
Managing / Taking Risk is our key forte among others